Last verified 5 November 2026.
Connectivity as a benefit is an employer-arranged program that gives employees access to mobile service under a defined funding and support policy. Employees, employers or both can pay for the service. It becomes a useful workplace benefit only when eligibility, subscription ownership, privacy boundaries and exit rules are written down before a discounted plan is offered.
It is not a tax category, a device-management feature or a promise that every employee will spend less. This guide covers what employees receive, who pays, what work the program creates, how a healthcare employer would apply it, and how to pilot it. For how personal phones fit the workplace more broadly, start with the enterprise BYOD guide. HR, finance, procurement and IT should agree on the decisions below before a stipend is replaced.
What is connectivity as a benefit?
Connectivity as a benefit organizes mobile-service access around an employee group and its needs. The offer can include a selected plan catalog, an employer contribution, enrollment support and ongoing administration. The label describes a delivery model, not a classification for tax or device control.
A benefit offered as a personal choice differs from mobile service required to do a job. A field worker who depends on dispatch needs a supported operating arrangement. An employee choosing an optional travel package needs clear purchase and support terms. Keep that purpose visible when you decide eligibility, funding and fallback options.
Document what the offer actually includes. A plan may supply data without a phone number or voice service. Device purchase, repair, insurance, app support and account recovery may sit outside the subscription. An enrollment page should state these boundaries before an employee commits.
Definition. A connectivity benefit combines an offer with operating rules. A discount alone does not establish who supports the employee, who owns the number or who resolves a billing dispute.
Which funding model fits your workforce?
Funding can be employee-paid, shared or employer-paid, and a stipend or reimbursement can remain the right answer for some groups. Choose against the program’s purpose, the work the employee must do and the administration you can support. Compare the actual arrangements instead of assuming a managed plan is always better.
| Arrangement | Funding path | Decision to resolve |
|---|---|---|
| Employee-paid selected offer | Employee purchases an available plan | Offer eligibility, cancellation and support boundaries |
| Shared funding | Employer contributes; employee pays the agreed remainder | Contribution limits, settlement and failed-payment handling |
| Employer-paid service | Employer funds the approved service | Role eligibility, service ownership and exceptions |
| Stipend or reimbursement | Employer pays an allowance or reimburses an approved expense | Required evidence, approval, payment and periodic review |
These are funding patterns, not tax categories or a ranking of cost effectiveness. Choose an employee-paid offer when the purpose is optional access and the terms suit the group. Choose shared funding when the contribution and settlement rules can be explained plainly. Choose employer-paid service when the business needs direct responsibility for an approved subscription. Keep reimbursement where an employee’s existing arrangement still suits the role.
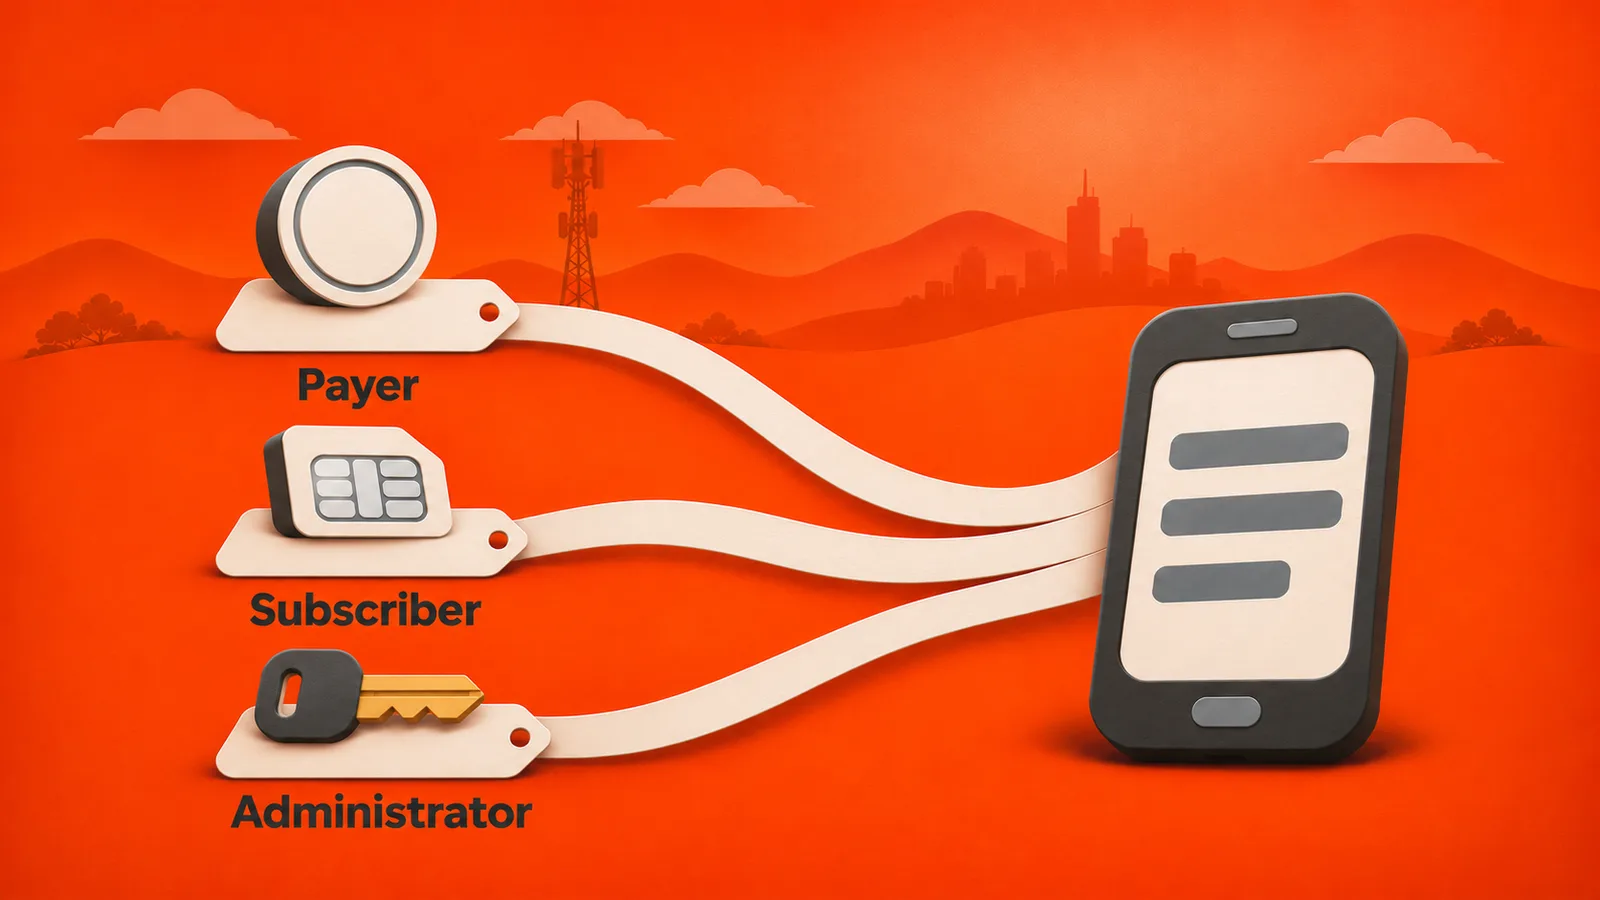
Funding does not decide the contract holder. An employer can contribute without owning the employee’s number, and a personal device can carry an employer-owned service. Record the subscriber, payer and authorized administrator separately, and tie those records to plan changes and invoices.
Key takeaway. Decide purpose, payer and service owner separately. A benefit that works as an optional personal purchase may not meet the operating needs of a business-critical role.
What belongs in the employee mobility policy?
An employee mobility policy should define eligibility, covered service, contributions, device requirements, support, privacy and what happens when participation ends. Explain the employee’s responsibilities before enrollment. Where personal devices are involved, the funding agreement and the device-management notice are distinct decisions. Payment does not grant unrestricted access to the phone.
Write down which roles and locations qualify, who approves exceptions and when eligibility is reviewed. Define plan changes, damaged devices, travel, usage beyond the allowance and number transfers, and say what happens during leave or a role change. A policy that answers enrollment questions but leaves ongoing decisions to individual managers will not hold.
The Office of the Privacy Commissioner of Canada’s BYOD guidance calls for assessing privacy risks and explaining organizational access. Apply that to the employee notice: show which service records administrators can see, who receives them and which device controls need a separate management arrangement. Do not ask for a complete personal bill when a narrower record meets the approved purpose.
NIST’s BYOD practice guide (SP 1800-22) treats security and privacy as architecture. Paying for connectivity does not enroll a device, isolate work apps or remove business data at departure. A dual-SIM or eSIM setup gives an employee separate mobile lines, which is also different from separate app or data controls.
Give employees a named support route for activation, billing and device problems. Say who can authorize a replacement service and what happens if a personal phone is incompatible. An employee should not discover these limits during a failed work task.
Watch out. Cancelling a mobile subscription does not remove work data or revoke every account session. Coordinate service changes with the identity and endpoint owners, and explain the approved action to the employee.
How do you compare the full operating cost?
Connectivity benefit cost includes the employer’s service contribution and the work of enrolling, supporting, changing and settling the program. Reimbursement processing is part of that work, and managed service has administration too. Compare the same employee group, service scope and period before saying one model costs less.
| Cost input | Evidence to collect | Comparison rule |
|---|---|---|
| Service and employer contribution | Current invoices, offers, allowance rules and commitments | Match coverage, voice and data scope, and period |
| Claims and settlement | Claim volume, handling time, approvals and exception records | Count recurring work under both models |
| Support and changes | Tickets, activations, replacements, transfers and departures | Include internal and contracted effort |
| Devices and tools | Device, repair, management and integration costs where included | Compare equivalent supplied capabilities |
| Transition and exit | Migration work, overlapping service and remaining commitments | Keep one-time and recurring costs separate |
This worksheet assumes no prices, labor rates or savings figures. Collect local inputs instead of importing a universal processing fee. For claim administration, estimate claim count multiplied by measured handling time and the relevant labor cost, and add exception work separately. Automated approval does not remove investigation, payment failures, employee questions or policy maintenance.
Inventory and invoice control carry over from telecom expense management. In a benefit program, match the enrolled population to the contribution and service records, and investigate charges after eligibility ends, duplicate payments and lines without a responsible owner. The business mobile cost and quality guide covers the cost side in more detail.
Keep employer cost and employee value separate. An employer can reduce its contribution by shifting cost to employees, which is not an efficiency gain. Record what participants receive, what they pay and how support performs next to the company’s expenditure. Do not turn an expected tax outcome into a savings line before specialist review.
What does a healthcare employer need from it?
Healthcare shows why the policy cannot stop at the monthly amount. Clinical staff use phones for patient charts, medication scanning, secure messaging, shift management and emergency alerts. When those phones are personal and funded by a flat stipend, the employer pays for part of the bill but controls none of the device. That gap is the strongest case for a managed benefit, and also the place where careless claims do the most harm.
In the United States, the HIPAA Security Rule requires covered entities to protect electronic protected health information with administrative, physical and technical safeguards. The technical safeguards cover access control, audit controls, integrity, person or entity authentication and transmission security, and some of them, encryption among them, are “addressable” rather than fixed. The HHS summary of the Security Rule and NIST’s guide to securing electronic health records on mobile devices are the places to start. The duty sits with the covered entity, so a stipend moves the cost to the employee without moving the responsibility.
| Question | Stipend on a personal phone | Employer-arranged, managed device |
|---|---|---|
| Who sets device standards? | The employee, within whatever the policy asks | The employer, from an approved device list |
| Can IT enforce a passcode, encryption or remote wipe? | Only if the employee accepts a separate management enrollment | Yes, when the device is enrolled before use |
| Is there a record of which devices reach clinical systems? | Usually partial | Inventory and access records are available to administrators |
| What does a lost phone cost the employer? | Unknown until it is reported | A defined wipe and replacement process |
| What happens when someone leaves? | Stipend stops; the device keeps its sessions until IT acts | Line and enrollment are closed in one documented step |
The right-hand column is a design target, not a default. Enrollment, remote wipe and app controls come from a device-management tool, not from the mobile plan, so confirm who operates them. A line that nobody deactivated after an employee left is a common leak in either model, which is why the cost check above looks for zero-use lines and charges after eligibility ends.
On tax, IRS Publication 15-B says the business use of an employer-provided cell phone can be excludable as a working condition fringe benefit when the phone is provided primarily for noncompensatory business reasons. The publication also lists examples of substantial business reasons, such as needing to reach employees for work emergencies. Whether a particular stipend or reimbursement qualifies depends on the facts, so do not assume a stipend is always taxable or a managed plan always excluded. Take the plan and payment flow to your tax advisor.
Build a health-system business case from your own device count, current stipend, incident history and turnover data rather than from a generic benchmark.
What needs specialist review before launch?
A connectivity benefit needs review of tax, payroll, reimbursement and employment-policy questions in every participating jurisdiction. The program’s name settles none of them. Give qualified specialists the actual contract, payment flow, business purpose and employee locations, then record the approved treatment before using it in payroll, employee communications or a financial comparison.
For a US arrangement, give the specialist the facts together with the IRS guidance linked above. For a UK arrangement, start with the GOV.UK guidance on mobile phones as expenses and benefits. These are materials for review, and this article does not classify a particular program or state a tax outcome.
Ask employment counsel to assess reimbursement obligations and policy wording for each location. A list of states is not a substitute for that review, and a change of payment route does not resolve every employment obligation. Where the covered staff handle regulated data, add the compliance owner too; the telecom compliance audit guide shows what evidence an auditor asks for.
Buyer checklist. Prepare the business purpose, participating locations, contract holder, payment flow and employee contribution rules. Ask the relevant specialists to approve the treatment and communications for that specific arrangement.
How should HR, finance and IT pilot the program?
A pilot should test the employee journey and the operating records together. Pick a defined group with a clear business purpose, then follow enrollment, use, support, settlement and exit. Set acceptance criteria before you start, and expand when the responsible teams can explain both successful delivery and unresolved exceptions.
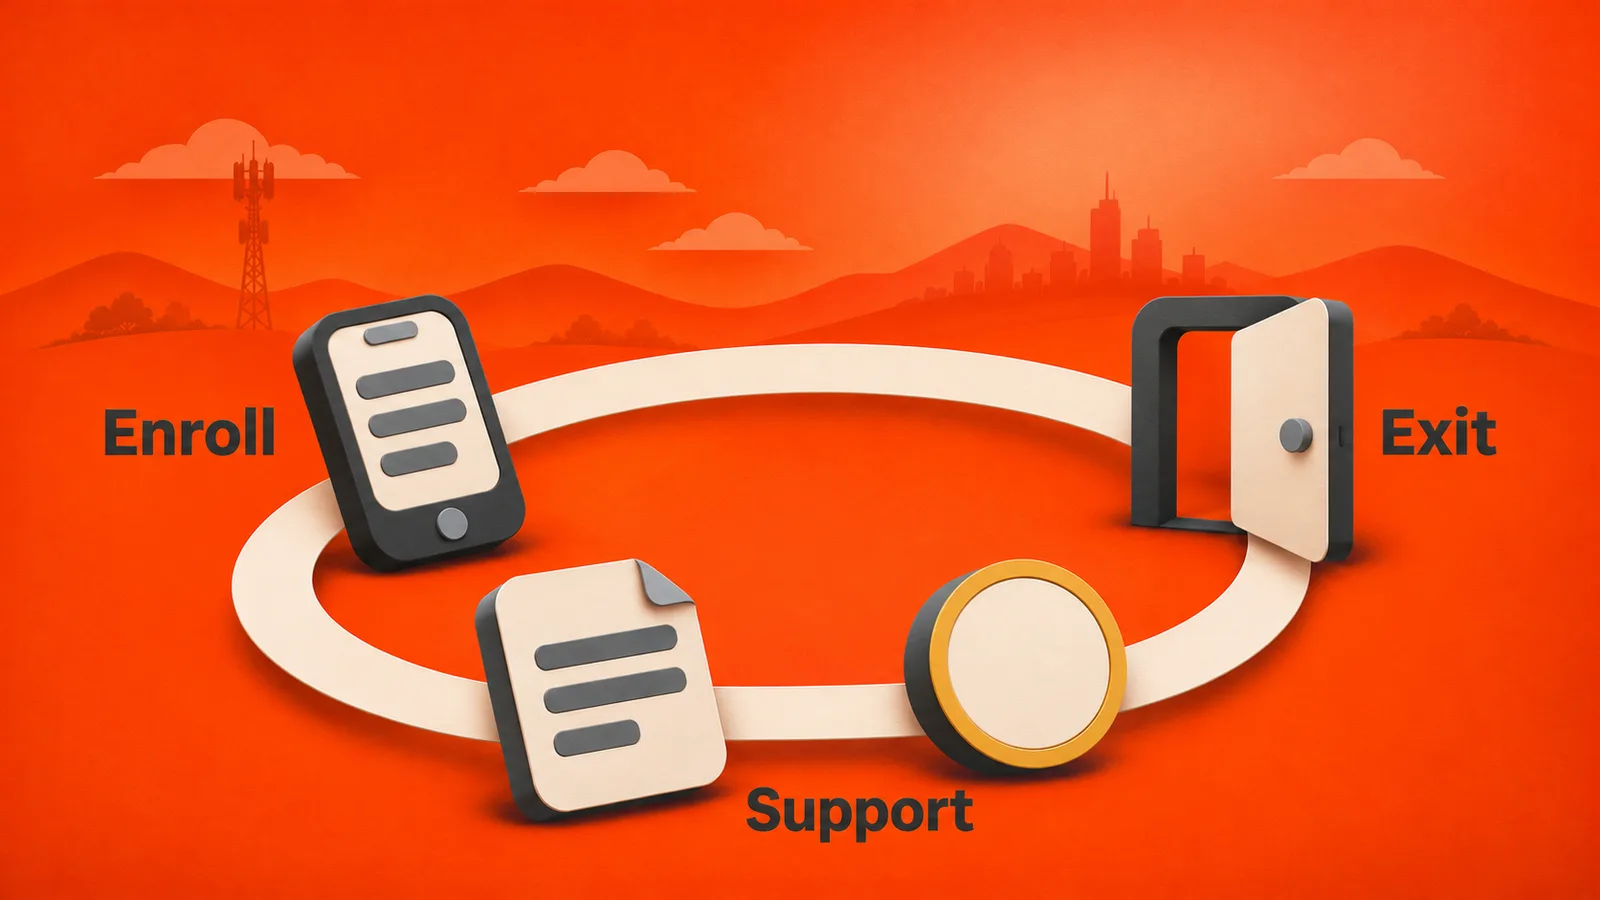
- Define the group. Record roles, locations, work needs and the alternative for employees who cannot participate.
- Approve the design. Confirm funding, contract ownership, privacy notice, support scope and specialist decisions.
- Test enrollment. Verify eligibility, compatibility, contribution disclosure and activation with representative users.
- Follow operations. Track support requests, failed payments, plan changes and unexpected charges.
- Test exit. Confirm number disposition, contribution end date, service action and final reconciliation.
The acceptance record should let each team see whether its own part worked.
| Owner | Pilot question | Acceptance evidence |
|---|---|---|
| HR | Do eligible employees understand the offer and alternatives? | Approved communications, enrollment and exception records |
| IT and mobility operations | Can employees activate and get the promised support? | Activation outcomes, tickets and resolved handoffs |
| Finance and payroll | Do contributions and charges follow approved rules? | Reconciled service, payment and invoice records |
| Program owner | Can participation end without unexplained service or charges? | Exit record with number, subscription and final-bill disposition |
Group size and timing should follow the scope and the operating capacity you have. The published RocketPhone enterprise MVNO case documents provisioning, subscriber management and billing delivered together by Spenza, an MVNE platform. Those capabilities are relevant to operating mobile services. The case is not an employee-benefit deployment and does not show a tax result or a retention improvement, so ask any provider, Spenza included, to demonstrate eligibility, contribution and exit workflows against your approved policy.
Conclusion
Choose a connectivity benefit by starting with the employee’s need and the operating responsibility behind it. Keep funding, subscription ownership and device control explicit, then compare the complete cost of the available arrangements, including the stipend you may already run. In healthcare, the deciding question is who can enforce the safeguards on the device that touches patient data, not how large the monthly payment is. A pilot should show where employees need help and where records fail to match, not merely count enrollments. Use what it finds to fix the policy before you expand, and expand only when HR, IT and finance can inspect the same evidence.
Connectivity as a benefit FAQs
Is a mobile stipend always the wrong choice?
No. A stipend or reimbursement can suit a defined employee group when the service need, evidence requirements and administration are understood. Compare it with employer-arranged service using the same scope and period. Do not assume either model is cheaper or legally preferable because of its label.
Can employees use their own phones?
Yes, if the program permits personal devices and the phone supports the required service and work controls. Confirm compatibility, carrier restrictions and support limits before enrollment. Provide an approved alternative for an incompatible device or an employee who cannot take part.
Can an employee keep a personal phone number?
Often the number can stay outside the work subscription, but it depends on the device and service. Avoid moving a personal number into an employer account without a clear ownership and exit agreement. Confirm transfer authorization and recovery arrangements before any porting request.
What happens when an employee leaves the program?
Follow the agreed exit policy for contributions, subscription ownership, number disposition and final charges. Confirm the provider’s effective service action rather than treating an HR status change as completion. Coordinate identity and work-data actions with IT.
Does a mobile stipend meet HIPAA requirements for healthcare staff?
A stipend pays for service but does not give the employer control of the device. The HIPAA Security Rule puts the duty to safeguard electronic protected health information on the covered entity, so it needs access, audit and transmission controls however the phone is funded. Ask your compliance officer how personal devices are covered.
Should the benefit include international travel?
Include travel when it matches the program’s purpose and the selected product terms. Define eligible destinations, approval, allowance, expiry, support and who pays for extra use. A domestic plan does not establish that voice, messaging or roaming is included.
Does an employer-paid plan require constant availability?
No. The service plan alone should not define work availability. Set response expectations, on-call arrangements and support hours in the approved employment and mobility policies, and explain them before enrollment.